(631)-271-3737,
QUEENS
(718)-751-0226
(516)-307-0262,
BROOKLYN
(347)-508-9316,
BOHEMIA
(631)-223-4502
(631)-271-3737,
QUEENS
(718)-751-0226
(516)-307-0262,
BROOKLYN
(347)-508-9316,
BOHEMIA
(631)-223-4502
Nassau County foreclosures run through the Supreme Court in Mineola on a fixed track, and where you sit on that track decides which move saves your house.
Free and confidential. No obligation.

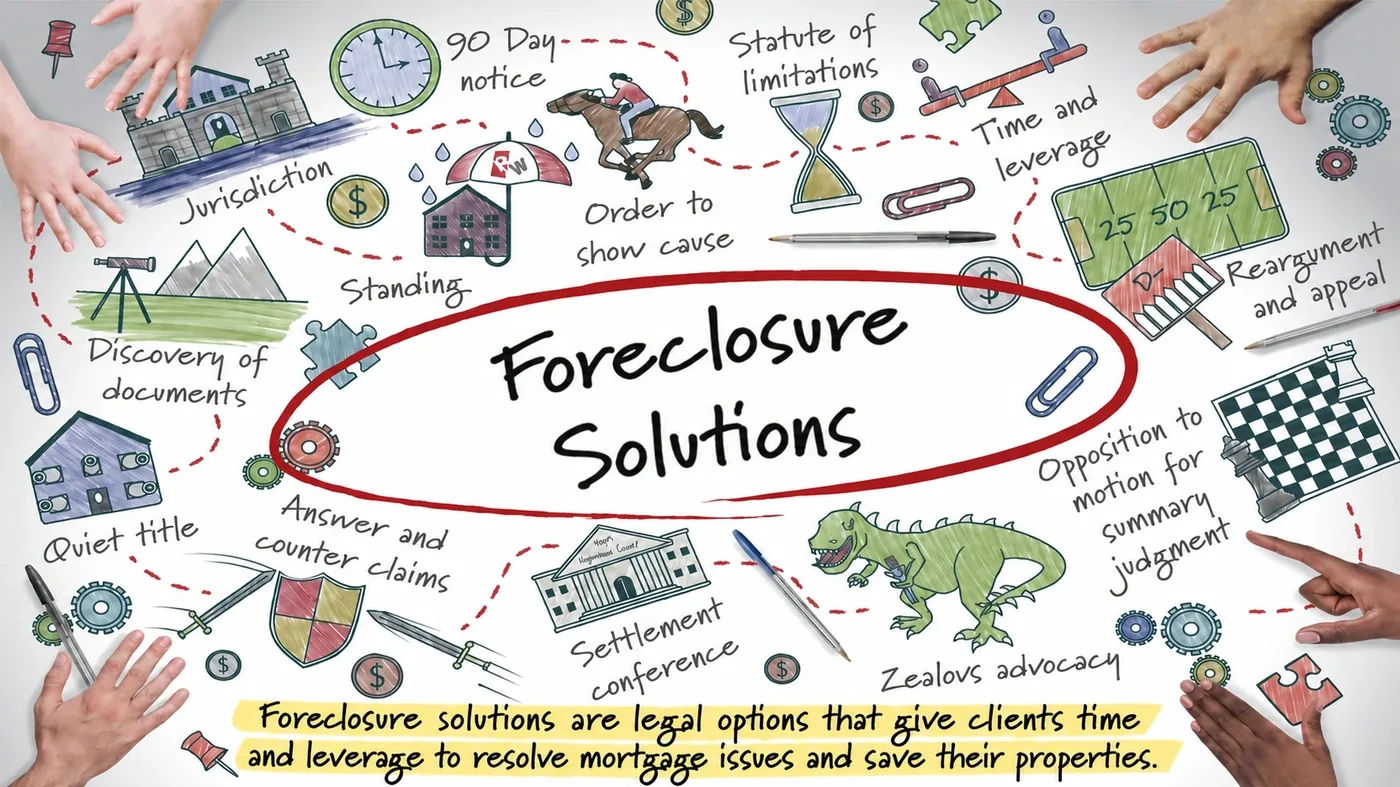
Foreclosure solutions are legal options that give clients time and leverage to resolve mortgage issues and save their properties.
A foreclosure lawyer in Nassau County defends the court case your lender filed and, when the calendar runs out, pulls the one lever that stops a sale outright. New York foreclosure is judicial, so the bank must sue you in the Nassau County Supreme Court in Mineola and prove its case, which opens real defenses: standing, notice defects, and the deadline to sue. Ronald D. Weiss, P.C. has worked this track since 1988, and because the same firm files bankruptcy, it can trigger the automatic stay that halts a scheduled auction when defense alone cannot. For the borough and non-county version of this service, see our Long Island foreclosure lawyer page.

A lender must send a 90-day and a 30-day notice before it can foreclose. Then your options: defend while seeking a loan modification, catch up or short sell, or use Chapter 13’s five years to reinstate.
Always answer a foreclosure complaint, or you face a default judgment. Five tools covered: a careful answer, affirmative defenses like lack of standing or dual tracking, counterclaims, a motion to extend or amend, and a motion to dismiss.
A lender’s motion for summary judgment does not end your case. Opposing it can show the court real disputes, like improper notice, defective assignments or accounting errors, and can delay or even stop the foreclosure.
Being served with a foreclosure complaint gives you information to use against the lender: wrong dates and amounts, gaps in assignments and endorsements, and defective signatures or verifications. Defended properly, the case can take a long time.
At foreclosure settlement conferences, the court oversees loan modification talks with your lender. Attend: modification is the main way these cases settle, your time to answer extends to 30 days after the first conference, and it buys time.
A motion for summary judgment asks the court to rule without a trial, but foreclosures often have factual disputes: service of process, proof the 90- and 30-day notices were mailed, good faith negotiation, standing and witness knowledge.
Practical steps when a foreclosure complaint is coming: you don’t have to open the door, record service attempts on a Ring camera, photograph how papers were left, keep the full document, and note where household members were.
In Bank of New York Mellon v. Dwayne Samuels, where our office represents the homeowner, the court held FAPA applies retroactively. If an old foreclosure was dismissed, the six-year statute of limitations may now bar the lender.
If you fell behind during COVID, New York lenders are now resuming those delayed foreclosures, and pandemic protections have expired. Foreclosure here is still a judicial process: the bank must sue you in court, and you have rights.
Loans pushed on elderly or ill borrowers with inflated fees, sky-high interest or unaffordable payments may be predatory. Under New York law, a court can limit or even cancel a loan found abusive or unconscionable.
Standing means the bank must show it owned or controlled your loan when the foreclosure began. Lenders can now prove it more easily by possessing the original documents, so this defense needs real questions about their paperwork.
Before a Nassau lender can file, RPAPL 1304 requires a 90-day pre-foreclosure notice sent to you in a specific form, and a defective notice can sink the whole case. Once the lawsuit lands in the Nassau County Supreme Court at 100 Supreme Court Drive in Mineola, New York adds a protection most states do not: a mandatory CPLR 3408 settlement conference where you and the lender must sit down and try to work out a modification before the case can move to judgment. Miss these off-ramps and the track runs to summary judgment, a referee’s computation, and a scheduled auction. We meet it at the step you are on, not the step a template assumes.
RPAPL 1304 requires a 90-day pre-foreclosure notice before any lawsuit can be filed.
The case is filed in the Mineola Supreme Court and routed to CPLR 3408 settlement conferences.
If unresolved, the case moves toward summary judgment, a referee’s computation, and a scheduled auction.

A foreclosure summons is the start of a case you are allowed to fight, and the strongest challenges are procedural. We answer the complaint and press the defenses the record often hands us: whether the plaintiff actually owned your loan when it sued (standing), whether the RPAPL 1304 notice was sent correctly, and whether New York’s six-year deadline to foreclose has already expired. This is court-floor foreclosure defense, not a phone script, and answering on time preserves every one of those arguments instead of letting a default judgment decide for you.
Foreclosure defense for Nassau County, steps from the Mineola courthouse.
Schedule a Free Consultation
Our focus is simple: keep good Nassau County families in the homes they have worked hard to build.
When a Nassau auction is days away and defense has run its course, a bankruptcy filing does what no letter can. The moment a case is filed in the U.S. Bankruptcy Court for the Eastern District of New York at Central Islip, the automatic stay takes effect by federal law and a scheduled sale must halt. A Chapter 13 then lets you cure the past-due balance over a court-approved three to five year plan while you keep making the regular payment, so the arrears that triggered the foreclosure get paid off on your schedule, not the bank’s. Because a bankruptcy lawyer in Nassau County sits in the same firm, the foreclosure defense and the stay are one coordinated plan.
Where a discretionary court stay can be denied, the federal automatic stay stops the sale by operation of law.
The CPLR 3408 conference is leverage, not a formality, and it is where most Nassau homeowners have their best shot at keeping the house on affordable terms. We prepare the financial package the lender’s loss-mitigation reviewers actually require, argue for a mortgage modification that lowers the payment, and press for forbearance, a repayment plan, or a short sale when a modification is not the right fit. Coming to the conference with an attorney and a complete file is the difference between a rubber-stamp denial and an approval.
More time, more leverage, and a real chance to keep your home.
Schedule a Free Consultation
No more sleepless nights over a sale date, just a clear path forward with an experienced attorney at your side.
Free ConsultationOur Nassau office sits at 34 Willis Ave in Mineola, minutes from the Supreme Court where your case is heard, and that proximity is not decoration: we file in that building, appear at those settlement conferences, and know how its parts run. You deal with the attorney handling your case, not a call center, and the price is a flat fee put in writing up front with nothing hidden, after a first consultation that costs you nothing. That is how a purpose-built Nassau page beats a directory listing and a defense-only firm working off a homepage.
As a full law firm rather than a settlement shop, we can litigate the case, and the firm’s attorneys have reversed lower-court foreclosure rulings at the Appellate Division, Second Department, and have filed emergency petitions the same day as a scheduled sale to stop it. Rated Avvo 10.0, Martindale-Hubbell 5.0, BBB A+, and selected to Super Lawyers in 2026.

The first consultation is free. The advice may be invaluable.
We defend homeowners from Garden City, Rockville Centre, and Manhasset to Great Neck, Freeport, Hempstead, and Long Beach, and no matter which Nassau town your home sits in, the foreclosure still runs through the Mineola Supreme Court where we appear.
Room to breathe again, with your home protected while you resolve the debt.
Talk to an AttorneyIn the Nassau County Supreme Court at 100 Supreme Court Drive in Mineola. New York foreclosure is judicial, so your lender has to file a lawsuit there and prove its case in front of a judge, which is exactly what gives you defenses and a mandatory settlement conference.
It is a court-ordered meeting, unique to New York, where you and the lender must try in good faith to work out a modification or other alternative before the case can move forward. Yes, attend it. Skipping it forfeits your best chance to keep the home and can let the case race to judgment.
Often, yes. Two tools can halt a scheduled sale: an Order to Show Cause asking the Supreme Court to stay the auction, and a bankruptcy filing, which triggers the federal automatic stay and stops the sale by operation of law the moment it is filed.
New York’s judicial process is slow, which works in your favor because each stage is a place to act. Here is the usual arc.
The strongest ones are procedural: whether the plaintiff owned your loan when it sued (standing), whether the RPAPL 1304 notice was mailed correctly and to the right people, and whether the six-year statute of limitations has already run. A defect in any of these can dismiss the case.
Filing stops the sale immediately through the automatic stay, but keeping the home long term means curing the default. A Chapter 13, filed in the Eastern District bankruptcy court at Central Islip, lets you pay the past-due balance over three to five years while staying current, so the reason for the foreclosure is resolved on a plan you can afford.
The first consultation is free, and the firm works on a flat fee set in writing with no hidden costs, so you know the price before you commit. In many cases the goal, a lower payment or a cured default, is what makes the fee pay for itself.
How our attorneys help you save your home and resolve mortgage debt.
Free consultation. Available 24/7 at 888-4-U-NEW-START, or reach the Mineola office at 516-307-0262.