(631)-271-3737,
QUEENS
(718)-751-0226
(516)-307-0262,
BROOKLYN
(347)-508-9316,
BOHEMIA
(631)-223-4502
(631)-271-3737,
QUEENS
(718)-751-0226
(516)-307-0262,
BROOKLYN
(347)-508-9316,
BOHEMIA
(631)-223-4502
Fight to keep your Brooklyn home
Behind on the mortgage or facing a Thursday auction?
Chapter 13 can halt the sale and give you up to five years to catch up.
Free consultation, in person or by phone.


A Chapter 13 plan for your Brooklyn home
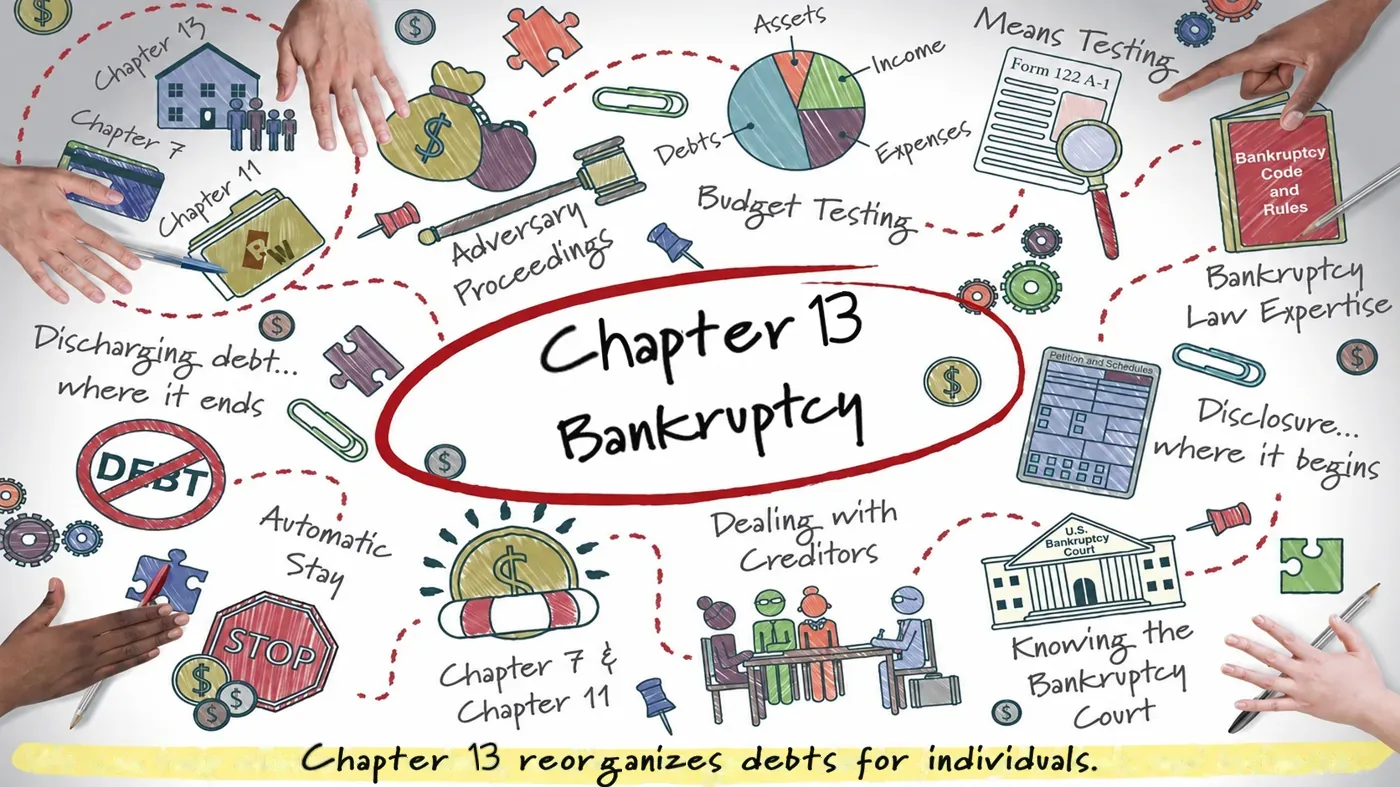
Chapter 13 reorganizes debts for individuals.
A plan to catch up, not give up

Chapter 13 is a court-approved plan of 3 to 5 years that can let people with steady income catch up on a mortgage and other debts while keeping their property.
Brooklyn cases are filed at the U.S. Bankruptcy Court for the Eastern District of New York, in the Conrad B. Duberstein U.S. Courthouse on Cadman Plaza East, the district's courthouse for Brooklyn, Queens and Staten Island.
Our main Chapter 13 guide covers the chapter in full. Here's how it runs in Brooklyn, starting with whether it fits you.
Chapter 13 turns a sale date into a payment plan.
Steady income, serious debt
Chapter 13 fits people with regular income (a paycheck, a pension, Social Security or a business) and something worth protecting. That usually means one of these:
To qualify, you need regular income and debts under the federal limits: under $526,700 unsecured and under $1,580,125 secured, for cases filed on or after April 1, 2025. Those limits adjust every three years.

If Chapter 7 might fit instead, compare Chapter 7 and Chapter 13 side by side or read about Chapter 7 bankruptcy. We weigh both against your real numbers.
Too much income for Chapter 7 isn't a dead end. It can be the way into Chapter 13.
Thursday comes fast

Kings County holds its foreclosure auctions every Thursday at 2:30 pm, at Kings County Supreme Court. If your home is on that calendar, you're counting days, not months.

Filing Chapter 13 before the auction triggers the automatic stay, which by law generally halts the sale. An earlier bankruptcy can change that, so tell us about any. We file emergency petitions within 24 to 48 hours, the same day if necessary.
We have filed on the same day as a scheduled sale and stopped it. Halting the sale is step one. The plan is built to keep you in the home, paying down the arrears while our Brooklyn foreclosure attorneys watch the state case.
If bankruptcy isn't the right move, an order to show cause can ask the court to halt the sale while real problems with it are reviewed. Either way, the sooner you call, the more options you keep.
A sale date is a deadline, not a verdict.
From filing to a fresh start

Your free consultation.
We go through your income, debts, home and any sale date, and sketch the plan.

Filing.
Your plan goes on the court's own Chapter 13 plan form. Plans that ignore the Eastern District's local rules may not be confirmed, so we build to them.
The trustee.
The Eastern District has one Chapter 13 standing trustee (Krista M. Preuss, as of 2026). You pay the trustee monthly, online or by bank check, certified check or money order.
The meeting of creditors.
Across the Eastern District it's held on Zoom (rare in-person exceptions), so you join from home. We prepare you before it.

Confirmation.
A judge reviews your plan and, if it meets the rules, confirms it. Creditor objections are due 7 days before the hearing, so we see them coming.
Three or five years.
Income below the New York median for a household your size usually means a 3-year plan; above it, generally 5. You pay the plan and stay current on your home.

Discharge.
Finish the plan, and the court wipes out the qualifying debt it didn't pay.
Every step has a rule. We know them, so you don't have to.

Our experience, creativity and empathy allow us to legally represent you, effectively and affordably.
Book My Free ConsultationCo-op owners are covered too
New York's homestead exemption shields a set amount of equity in the home you own and live in. It covers co-op shares and condo units as well as houses (CPLR 5206).
For Kings County homeowners, that amount is $204,825, effective April 1, 2024.
Have a second loan on the property? See what happens to a second mortgage in bankruptcy.
Equity above the protected amount doesn't mean losing the home in Chapter 13. It shapes the plan instead: unsecured creditors must get at least what they would in a Chapter 7, so extra equity can mean a larger payment.
In Chapter 13, the whole plan is built around keeping the home.

Negotiate with your bank, with a judge watching
The Eastern District runs a Loss Mitigation Program: a court-supervised forum where homeowners facing foreclosure negotiate with their lender.
It's available in many Brooklyn cases, depending on the judge your case is assigned to, because the court lists the judges whose cases it covers. We check how that applies to you at the consultation.

Inside it, you and your lender can work out a modification, a refinance, a forbearance, a short sale or a surrender. In Chapter 13, we flag it in your plan and file a separate request to start it.
While loss mitigation runs, a lender's motion to lift the stay is generally held off. That gives the talks room to work.
Our experience and resources allow us to obtain mortgage modifications that were previously denied.
Two courts, one team
A Brooklyn homeowner in Chapter 13 often has two cases at once: the bankruptcy in federal court on Cadman Plaza East, and the foreclosure in Kings County Supreme Court. Filing pauses the foreclosure. It doesn't erase it.

We handle both: the bankruptcy that pauses the foreclosure, and the foreclosure defense itself, from the first answer through trial and appeal.
Our Brooklyn bankruptcy attorneys and foreclosure team build one strategy for both cases, not two offices trading phone calls.
Our appeals record backs it. In FV-I, Inc. v Samuels (2025), a Long Island homeowner's case from Nassau County, we represented the homeowner. The Appellate Division, Second Department threw out the foreclosure judgment and dismissed the case because the lender waited too long to sue.
Prior results do not guarantee a similar outcome.
Two cases, one team watching both.
Free to ask, clear before you sign

Chapter 13 attorney fees are typically built into the court-approved repayment plan. That spreads our fee across the same monthly payment that catches up your arrears.
The consultation is free. Not a charge folded into your fee later: free. Every cost is disclosed in a written agreement before you sign anything.
Our legal consultations are free, but our advice may be invaluable.
Trained in bankruptcy court from day one

Ronald D. Weiss clerked for U.S. Bankruptcy Judge Prudence B. Abram (Southern District of New York), held NYU Law's John J. Galgay Fellowship in Bankruptcy and Reorganization Law, and published on the bankruptcy court's contempt power.

Ron does the consultations himself, in person or by phone. Behind him is a full firm (attorneys, paralegals and a foreclosure team) working your case together from start to finish.

Practicing since 1988 and admitted in the Eastern District of New York, the federal court that hears Brooklyn bankruptcy cases.

Meet at our Brooklyn office at 26 Court Street in Downtown Brooklyn, Suite 2206, by appointment.

Consultations in English and Spanish. Our team also speaks Hindi, Urdu and Russian.
Avvo 10.0 Superb · BBB A+ · Super Lawyers 2026 · Martindale-Hubbell Client Champion Platinum 2026
A judge's former clerk reads your plan the way the court will.
Not sure Chapter 13 is your answer?
Tell us what's happening. We'll weigh Chapter 13 against Chapter 7, a loan modification and a foreclosure defense, then show you the plan that fits your numbers.
Every debt challenge is unique, and every debt solution we design is customized for that specific client's situation.

Up to the day of the sale, but don't wait for it. A case filed before the Thursday 2:30 pm auction generally halts it. Tell us about any earlier bankruptcy, because a recent one can change that. Call as soon as you have a sale date.
Most of it is the plan itself, which runs 3 to 5 years:
Usually not. Meetings of creditors in Eastern District Chapter 13 cases are held on Zoom, with rare in-person exceptions. If anything does call you to Downtown Brooklyn, the court is at 271-C Cadman Plaza East and our office is at 26 Court Street.
Chapter 13 is built to let you keep it. New York's homestead exemption shields a set amount of equity in a co-op or condo you live in, as well as a house: $204,825 in Kings County (effective April 1, 2024). Equity above that generally means a larger plan payment rather than a sale.
Three numbers set it, and we work them out with you:
Example only: $18,000 behind, spread over 60 months, is $300 a month toward the arrears, on top of your regular mortgage.
Mostly, you live on the budget your plan is built on. Three rules come with it:
It depends on your judge. The Brooklyn bankruptcy court's Loss Mitigation Program, where you and your lender negotiate a modification under court supervision, is available in many Brooklyn cases, depending on the judge your case is assigned to. We check that at your consultation. Not in bankruptcy? See how we handle mortgage modifications on their own.
Four things put a case at risk, and each has a fix:
You can, but Chapter 13 is one of the hardest chapters to do alone: a plan of up to five years on the court's own form, a trustee checking every number, and often a foreclosure running alongside. Each one is a place a case can stall.
The consultation costs nothing. After that, Chapter 13 attorney fees are typically built into the court-approved repayment plan. The court's own filing fee is separate from our fee, and we walk you through it at the consultation.
It's built not to. Your payment comes from what's left after allowed living expenses, so the plan covers your bills first. The catch is time: the plan runs 3 to 5 years and the filing shows on your credit, though most of our clients see measurable credit improvement within 12 months of filing.
How the chapter works across New York.
Every bankruptcy option for Brooklyn.
Fighting the Kings County foreclosure.
26 Court Street, by appointment.
Ready to keep your home?
One call gets you a free consultation, a plan built on your real numbers, and a filing within 24 to 48 hours if a sale is close.
Available 24/7.