Long Island Chapter 13 lawyer

One plan for all of your debt

Mortgage arrears, the car loan, back taxes and credit cards: Chapter 13 can gather them into one monthly payment, built around keeping what you own.

888-4-U-NEW-START (888-486-3978)

The consultation is free, by phone or at one of our offices.

Ronald D. Weiss, Esq. · Former U.S. Bankruptcy Court law clerk · NYU Law bankruptcy fellow · Since 1988
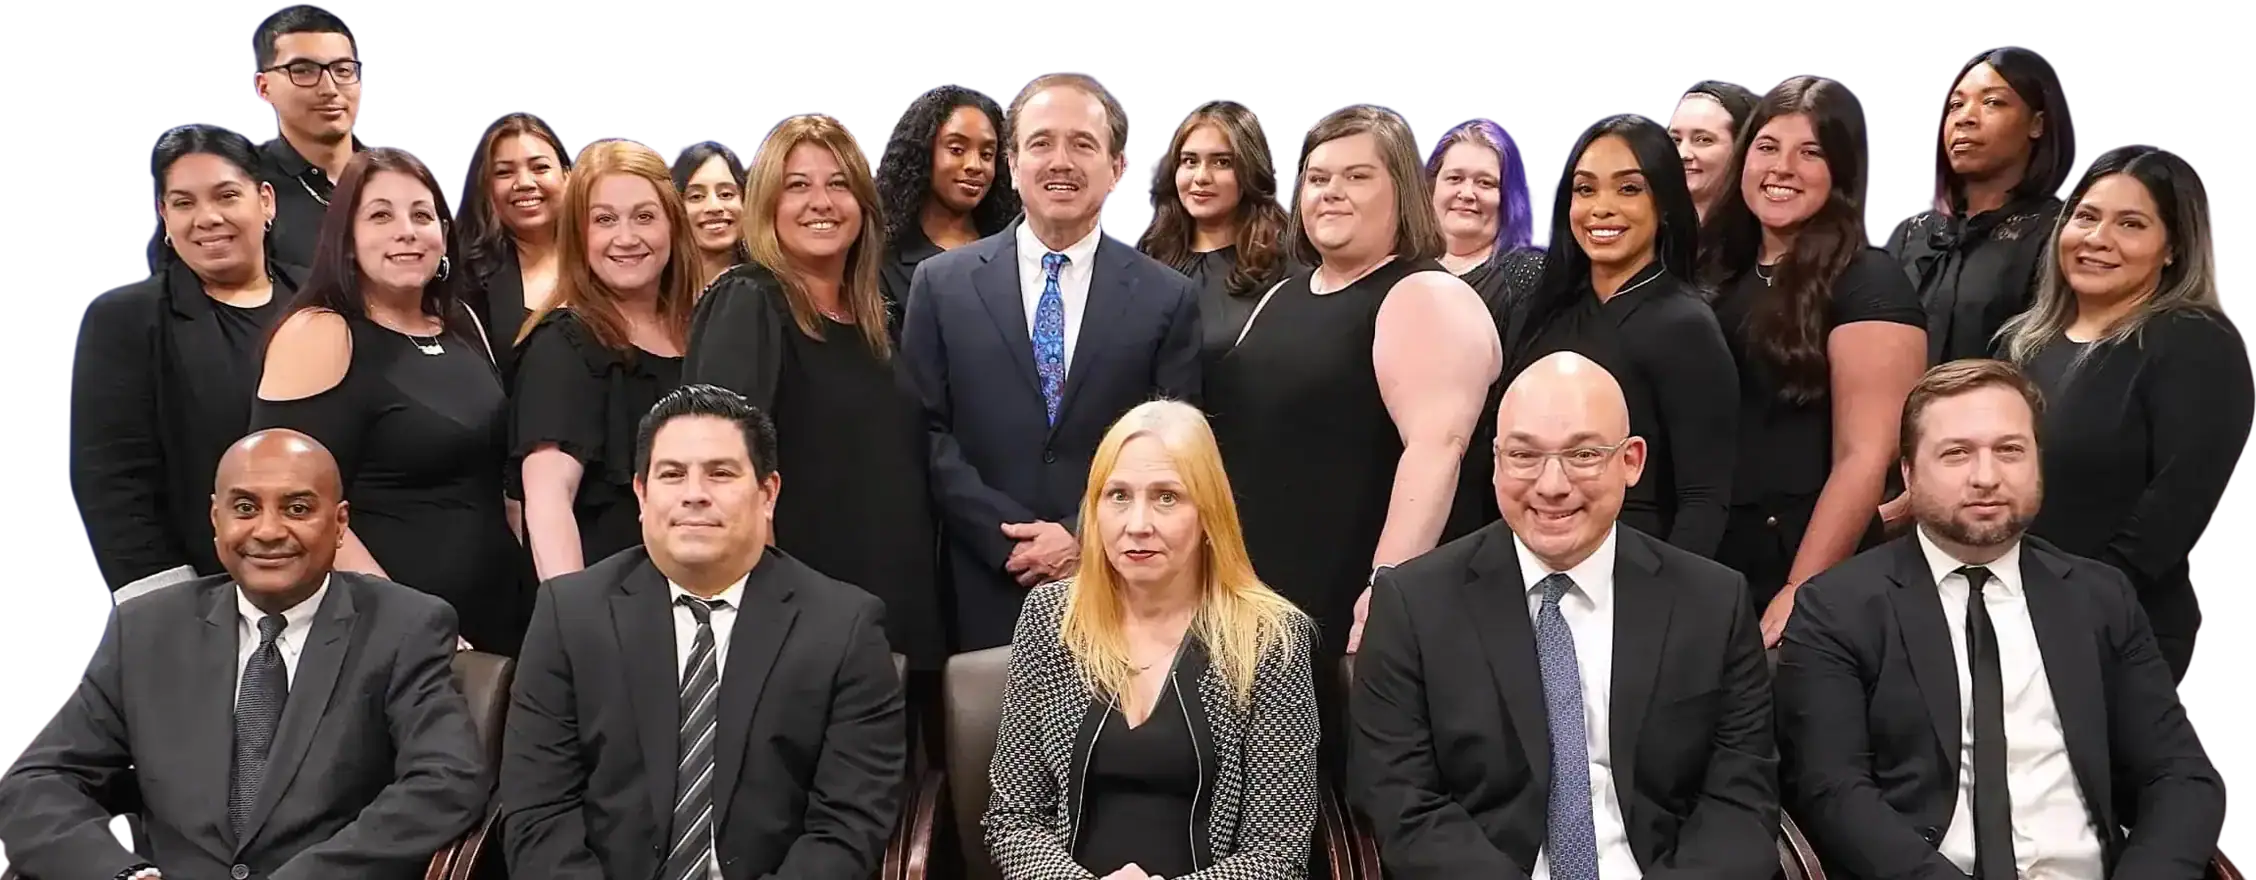
The Ronald D. Weiss legal team
Offices in Melville, Mineola and Bohemia
Consultations by phone or in person
Available 24/7
Hablamos Español
Google Reviews - 5.0 starsFacebook Reviews - 5.0 starsBBB A+ RatingLawyers.com - 5.0 starsAvvo 10.0 Superb RatingSuper LawyersMartindale-Hubbell Client Champion Platinum 2026BirdEye - 4.9 stars
Excellent ★★★★★ 5.0 | 395 reviews
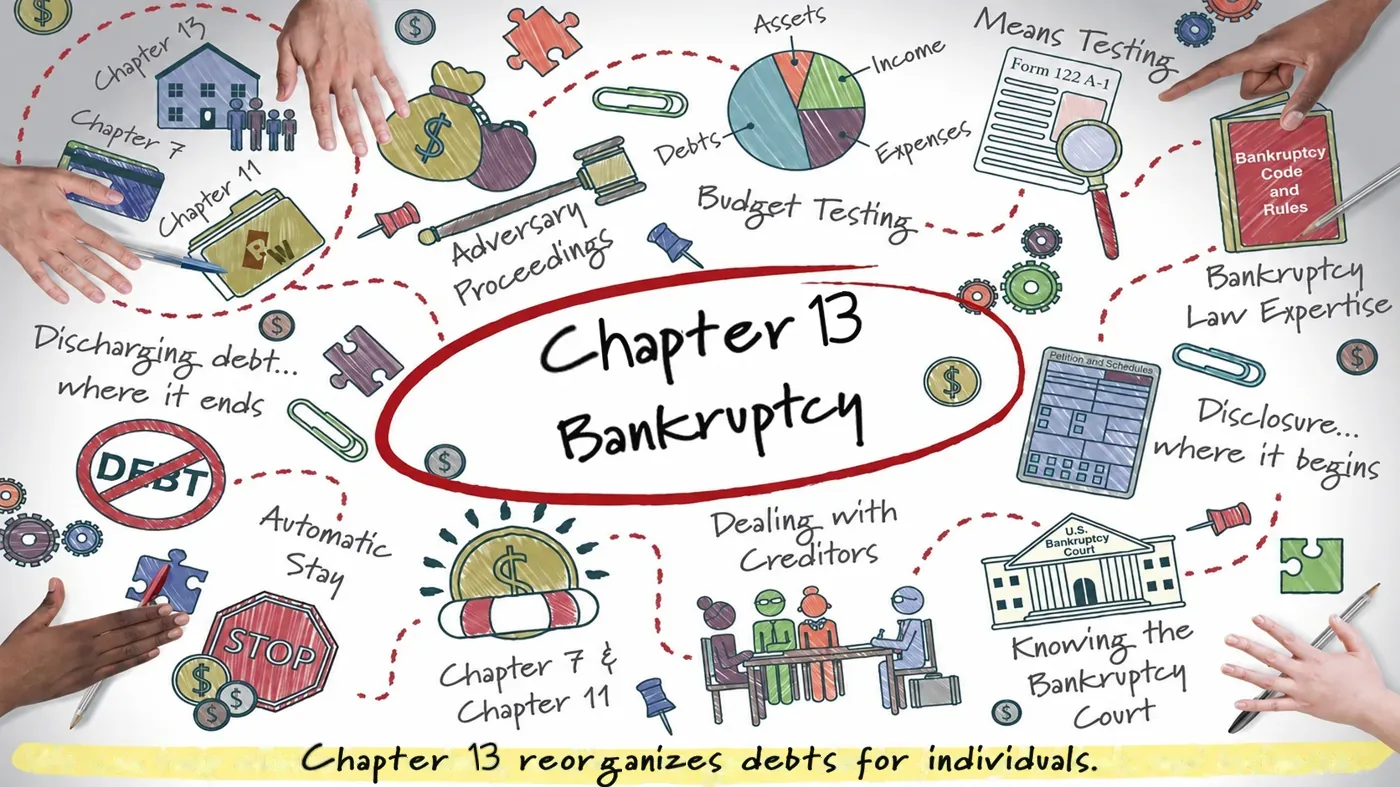
Chapter 13 Bankruptcy illustration

Repay over time and keep what you own

Chapter 13 reorganizes debts for individuals.

  • One payment to the trustee
  • Arrears spread over up to five years
  • A discharge when the plan is complete

How Chapter 13 works in New York

Three to five years, then a discharge

Hourglass illustration

Chapter 13 is a court-approved repayment plan for people with regular income: you make one monthly payment for 3 to 5 years to a trustee, who pays your creditors. Of every bankruptcy chapter we handle, it's the one built around keeping property.

Filing triggers the automatic stay, which generally halts collection calls, lawsuits, garnishments and foreclosure while the plan runs. Make the last payment, and the court discharges the qualifying debt the plan didn't pay in full.

In New York, every Chapter 13 is a federal case, but state law sets how much home equity you can protect. That mix is why the details matter, starting with whether you qualify.

Three kinds of plans

Ron's video below walks through them: a catch-up plan for missed payments, a plan built around a mortgage modification, and a percentage plan that pays part of your unsecured debt. All three are bankruptcy reorganization plans a judge has to confirm.

Chapter 13 Plan Options

Chapter 13 trades a pile of due dates for one plan with an end date.

Chapter 13 attorney fees, court costs and who qualifies

The numbers, before you file

Under $2.75M
in secured and unsecured debt combined, for cases filed after November 10, 2026
1 limit
replaces the old separate caps on secured and unsecured debt
$313
court filing fee as of 2026, payable in installments with the court's approval
3 to 5 years
plan length, set by your household income

To qualify, you need:

  • Regular income: wages, self-employment, a business you run yourself, a pension or benefits.
  • Debts under the limit above, $2.75 million in secured and unsecured debt combined, counted on the day you file.
  • Credit counseling from an approved agency in the 180 days before you file.
  • No recent case thrown out because you missed court or ignored the court's orders. A dismissal like that in the past 180 days can block a new filing.

Over a limit? Another chapter may still fit, and we weigh it with you at the consultation.

What it costs to start:

  • The consultation is free.
  • Chapter 13 attorney fees are typically built into the court-approved repayment plan.
  • The court's filing fee is separate from our fee: $313 as of 2026. An individual can ask the court to let it be paid in up to four installments.
  • Every cost is disclosed in a written agreement before you sign anything.
Ask If I Qualify for Chapter 13

Know what you qualify for, and what it costs, before day one.

Pie graph illustration

Who a Chapter 13 bankruptcy attorney can help

When repaying beats wiping out

Seesaw illustration

Chapter 13 tends to make sense when you have income to fund a plan and something Chapter 7 would put at risk. It usually fits one of these:

  • Behind on a mortgage and set on staying in the home.
  • Behind on a car loan, with the lender talking about repossession.
  • Owing back property taxes. A plan can spread them across up to five years, with any tax-lien foreclosure or auction stayed while it runs.
  • Earning more than the means test allows for Chapter 7.
  • Sued by a creditor, or watching a garnishment take part of every paycheck.

Chapter 13 or Chapter 7?

Chapter 7 eliminates most debts, usually in a matter of months. But it has an income test, and a trustee can sell property your exemptions don't cover. Chapter 13 takes years and is built around keeping property.

We run your numbers both ways. If they point to a Chapter 7 case instead, we'll tell you.

Bankruptcy Means Testing

The right chapter is the one your budget can finish.

The Long Island Chapter 13 process at Central Islip

What the court asks, and when

Long Island Chapter 13 cases are filed with the U.S. Bankruptcy Court for the Eastern District of New York at the Alfonse M. D'Amato U.S. Courthouse, 290 Federal Plaza, Central Islip. Here is the path a case takes there.

Gears illustration
  1. Counseling and a consultation.

    You complete credit counseling, and we go through your income, debts, home and car to sketch the plan.

  2. Petition and schedules illustration

    The petition and the plan.

    The court publishes its own Chapter 13 plan form, and a plan that strays from the district's rules risks not being confirmed. We draft to both.

  3. Fourteen days for the paperwork.

    Your schedules, budget and the rest of the papers are due within 14 days of the petition. If they're late, the court can dismiss the case.

  4. Payments start within 30 days, even before the plan is approved.

    They go to the Chapter 13 trustee, Krista M. Preuss (as of 2026), whose office is in Jericho, online through TFSBillPay.com or by mailed bank check, certified check or money order.

  5. U.S. Bankruptcy Court illustration

    The meeting of creditors, by video.

    For Central Islip cases filed on or after October 1, 2023, it's held on Zoom, with rare in-person exceptions. The trustee questions you under oath, and we prepare you for it.

  6. Confirmation.

    A judge decides whether the plan is workable and meets the Bankruptcy Code's standards. If it isn't confirmed, a modified plan can be filed.

  7. Three or five years.

    Household income under the state median for your family size usually means a 3-year plan; above it, 5. Here's more on how long a Chapter 13 plan lasts. Check with the trustee before taking on new debt.

  8. Crossed-out debt illustration

    A course, then the discharge.

    Proof of a personal financial management course is due within 60 days after the first date set for the meeting of creditors. Finish the payments, and the court enters your discharge.

Bankruptcy Petitions, Schedules, Statement of Financial Affair & Disclosure

The first weeks are deadlines and paperwork. After that, it's mostly one payment a month.

A happy family laughing together in their kitchen

Bankruptcy is the most effective way to deal with debt.

Book My Free Consultation

What filing Chapter 13 bankruptcy puts on hold

Breathing room from the day you file

Stop sign illustration

The automatic stay begins the moment your petition is filed, with no judge needed to turn it on. While it lasts, creditors generally can't:

  • Call you demanding payment.
  • Start a lawsuit or keep pressing one.
  • Garnish your wages or freeze your bank account.
  • Repossess your car.
  • Move a foreclosure forward.

It has limits. Some actions aren't covered, and a case of yours dismissed within the past year can cost you the stay's protection, so tell us about any earlier filing. More on how the automatic stay protects you in Chapter 13.

If a foreclosure is already underway

Timing decides it. Filing before the sale generally halts it, but if the sale is completed under state law before you file, you can still lose the home.

We file emergency petitions in 24 to 48 hours; when a sale can't wait, the same day. The foreclosure side has its own page: using Chapter 13 to stop a foreclosure.

Automatic Stay

The stay buys time. The plan decides what that time is for.

Keeping your home and car in a Chapter 13 plan

What you keep in Chapter 13

Your home and its equity

New York law protects a set amount of equity in the home you live in, whether it's a house, co-op shares, a condo unit or a mobile home (CPLR 5206).

In the top tier, which takes in all five boroughs, Long Island and three counties north of the city, that amount is $204,825, a figure set on April 1, 2024.

Equity above that amount doesn't by itself force a sale in Chapter 13. It raises the floor for what unsecured creditors must receive, which can mean a larger payment.

The mortgage and the car

Missed mortgage payments can be caught up over the plan, as long as you keep making the regular payments that come due. A car loan or other secured debt can be stretched over the life of the plan, which may lower the payment.

Second mortgages, judgment liens and co-signers

A relative who co-signed a personal or household debt with you is generally shielded too: the creditor needs the court's permission to pursue them while your plan runs. Read about the Chapter 13 co-debtor stay.

Selling instead of catching up

When the household income can't support a catch-up plan, home equity can. In a Chapter 13 sale plan, the goal of the case is to sell: you get time to market the house, about six months as a rule, while the monthly payments stay modest.

Once a buyer signs a contract, the sale funds the plan. You sell at a price you agreed to rather than losing the equity at a foreclosure auction, even when another office has told you there's no way forward.

A loan modification

Whether the court's Loss Mitigation Program, a court-supervised negotiation with your lender, is open to you turns on which judge gets your case. We find out how it applies to you at the consultation.

Where it isn't open, our Mortgage Modifications department can still pursue a modification with the lender.

Ask About Keeping My Home

Equity, car, co-signer, second loan: each has its own rule inside the plan.

Castle illustration

Find a Chapter 13 lawyer for your borough or county

Where you live changes the details

Chapter 13 is federal law across New York, but the courthouse, the foreclosure calendar and the property-tax rules change with your address. This page covers Long Island.

Brooklyn, Queens and Staten Island cases go to the Eastern District's Brooklyn courthouse. Manhattan and the Bronx file in the Southern District, where Ron is admitted too.

New York State illustration

Who handles your Long Island Chapter 13 case

A founder who still takes the first meeting

Gavel illustration

Clerked for a U.S. Bankruptcy Judge

Ronald D. Weiss began his career clerking for U.S. Bankruptcy Judge Prudence B. Abram of the Southern District of New York.

At NYU Law he held the John J. Galgay Fellowship in bankruptcy law, and his article on bankruptcy courts' contempt power ran in the Bankruptcy Developments Journal.

People meeting at a table illustration

Ron meets you himself

Ron does the consultations, in person or by phone. After that you deal with an attorney directly, not an intake coordinator, and the same team stays with your case from filing to discharge.

House illustration

Three Long Island offices

Our main office is in Melville, on Route 110 near the Nassau/Suffolk line, and walk-ins are welcome there. Mineola and Bohemia see clients by appointment. Same-day consultations are available.

U.S. Bankruptcy Court illustration

Admitted in both federal districts

In practice since 1988 and admitted in 1992 to both federal districts: the Eastern, which hears Long Island cases, and the Southern. The firm belongs to the Nassau County and Suffolk County Bar Associations.

Sword and shield illustration

A Long Island appeals win

In FV-I, Inc. v Samuels (2025), a Nassau County homeowner's foreclosure, the Appellate Division, Second Department reversed the lower court and dismissed the case as time-barred. We represented the homeowner.

Prior results do not guarantee a similar outcome.

Handshake illustration

Hablamos Español

Consultations are available in Spanish, and our team also speaks Hindi, Urdu and Russian.

Avvo 10.0 Superb · BBB A+ · Super Lawyers 2026 · Martindale-Hubbell Client Champion Platinum 2026

A full firm behind you, and the founder across the table.

Your free Chapter 13 consultation with Ron

Every option, side by side

Tell us what you're behind on and what you want to keep. Ron sets Chapter 13 beside Chapter 7, a mortgage modification and a negotiated settlement, then shows you which one your numbers support.

Our legal consultations are free, but our advice may be invaluable.

Creative Legal Solutions to Your Debt Challenges video

Common questions for a Chapter 13 attorney

In five stages, all in federal bankruptcy court:

  1. Get credit counseling, then file a petition and a repayment plan.
  2. Start paying the trustee within 30 days of filing.
  3. Answer the trustee's questions at the meeting of creditors.
  4. A judge confirms the plan if it meets the Bankruptcy Code's standards.
  5. Pay for 3 or 5 years, then receive your discharge.
Melville Office exterior

Melville Office (Main Office)

Walk-ins Welcome
445 Broadhollow Rd, Suite CL-10
Melville, NY 11747
Get Directions

Chapter 13 lawyer on Long Island

Start with one conversation

Call any hour. Ron goes through your debts with you and puts every cost in writing, and when a deadline is close, the filing can move fast.

Available 24/7.

↑ Top