(631)-271-3737,
QUEENS
(718)-751-0226
(516)-307-0262,
BROOKLYN
(347)-508-9316,
BOHEMIA
(631)-223-4502
(631)-271-3737,
QUEENS
(718)-751-0226
(516)-307-0262,
BROOKLYN
(347)-508-9316,
BOHEMIA
(631)-223-4502
Keep your Nassau County home and the equity in it
Years of payments can leave a Nassau County house holding more equity than the law protects. Chapter 13 is built to let you keep it while you catch up.
888-4-U-NEW-START (888-486-3978)Click to callFree consultation, by phone or by appointment in Mineola.


In Nassau County, the equity changes the math
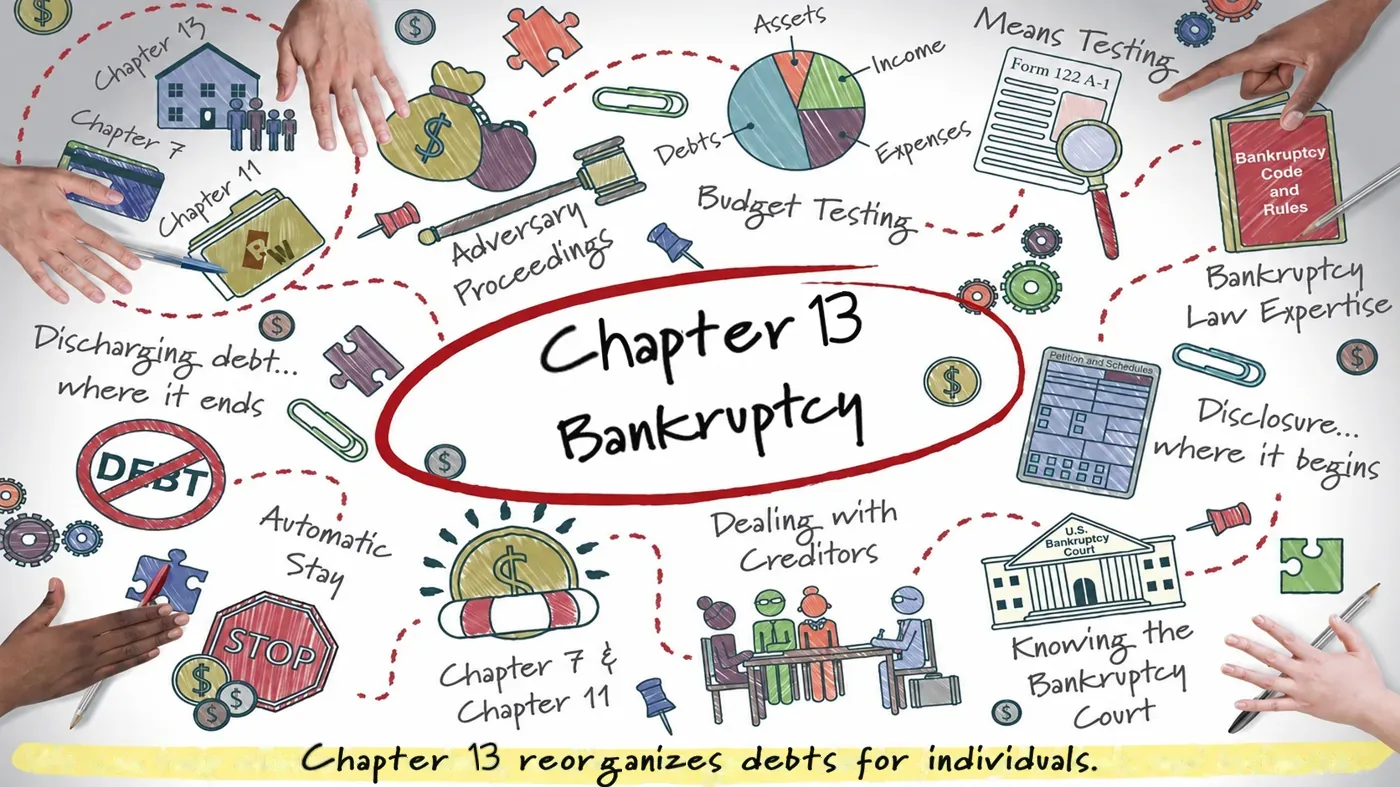
Chapter 13 reorganizes debts for individuals.
Central Islip, not Mineola

Chapter 13 in Nassau County works as it does anywhere: a court-approved plan, paid from your income for three to five years, while you stay in the house. Our main page covers the Chapter 13 process from start to finish.
The twist for a Nassau County filer: the case isn't heard in Mineola. It goes to the bankruptcy court's Central Islip courthouse at 290 Federal Plaza, in Suffolk County, which serves Nassau County and Suffolk County alike.
The Chapter 13 trustee who collects your plan payments, Krista M. Preuss as of 2026, has her office in Jericho, back in Nassau County. And for Nassau County cases filed since October 1, 2023, the meeting of creditors runs on Zoom.
Court in Suffolk County, trustee in Nassau County: that part is settled before you call. What shapes your plan is the equity in your house.
The court is out of county. The stakes are under your roof.
More house than the exemption covers

Nassau County is a county of owners. Census estimates put about 82% of its occupied homes in their owners' hands and the median home value at $684,700.
About 37% of Nassau County owners have no mortgage at all, by Census estimates, and about 9% carry more than one (a second mortgage or a home equity loan).
The line that matters is the state's homestead exemption. It shields a set amount of equity in your primary residence, and Nassau County sits in New York's top tier: $204,825 since April 1, 2024.
Run those numbers together. A paid-off house at Nassau County's median value holds more than three times what the exemption covers.

In Chapter 7, a liquidation, equity above the exemption is what a trustee can sell to pay creditors. Chapter 13 is designed around keeping the house, so that equity becomes a number in your plan instead.
A Chapter 13 plan has two parts, and only one of them feels your equity:
| Part of the plan | What it covers | How your equity affects it |
|---|---|---|
| Catch-up | Mortgage arrears (and car arrears, if you have them), spread out for up to five years on top of your regular payment | Very little: this part is set by the size of your arrears |
| Percentage | A share of your unsecured debts, such as cards and medical bills, with the rest discharged when the plan ends | Directly: your unsecured creditors must receive at least what a Chapter 7 would have paid them, so more unprotected equity can mean a larger share |
With a $684,700 median home, that floor can sit high. A second loan lowers it, because equity is what's left after every lien. That's why we run your numbers before anything is filed.
If there's no house to save, or little equity in it, wiping out debt under Chapter 7 in Nassau County may be the quicker route. We compare both at the consultation.
Equity matters in a second way when income runs short. If a catch-up plan is out of reach, a Chapter 13 sale plan lets you market the house yourself, usually over about six months on light monthly payments.
That way a Nassau County home's value goes to you, not to a sale on the Mineola courthouse steps.
Big equity is a reason to plan carefully, not a reason to panic.
A good salary, and still behind

Census estimates put Nassau County's median household income at $146,202. Two paychecks can lift a family over the Chapter 7 means test, the income check Ron explains in the video below.
Those incomes carry Nassau County costs to match. The median owner with a mortgage here spends $3,795 a month on housing (mortgage, taxes, insurance and utilities), another Census estimate.
Above that line, Chapter 13 stays open. Two more things a Nassau County household should know:
High income and high costs can both fit inside one Chapter 13 plan.
Any weekday, on the courthouse steps
In Nassau County, a referee can book a foreclosure auction for any weekday afternoon from 2:00 to 4:30 pm, on the hour or half hour, under the court's rules (revised November 12, 2024).
Every sale happens on the north side steps of the Nassau County Supreme Court, 100 Supreme Court Drive, Mineola. Bidders may join remotely since November 18, 2024, but the auction itself stays in person.
Auction calendars on eCourts are updated at least every Friday and are subject to change, and the day's list goes up near the north steps 45 minutes before the first sale.
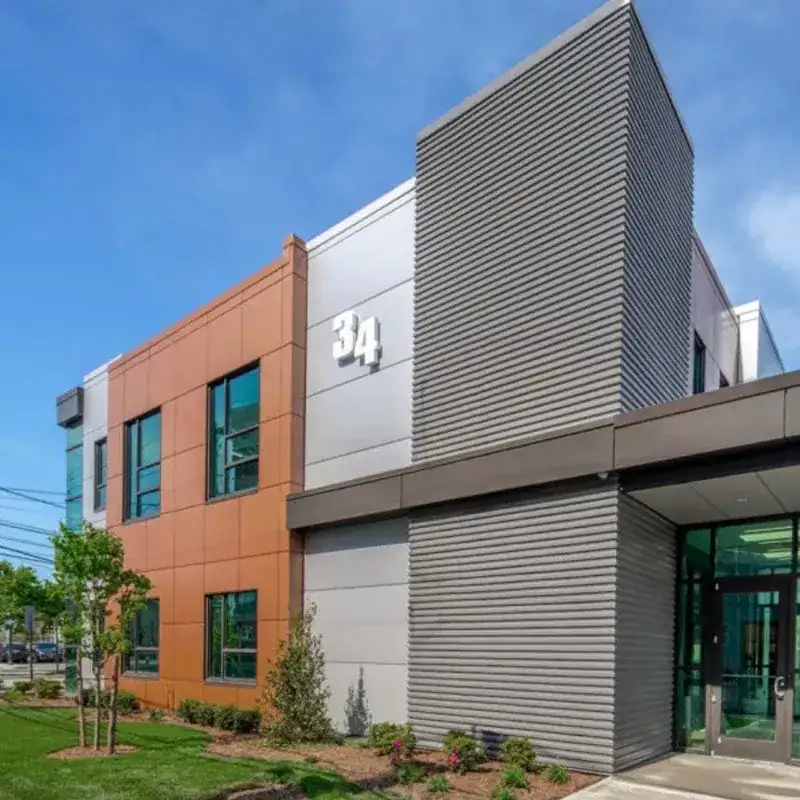
Our Mineola office, 34 Willis Avenue (by appointment), is in the same village as that courthouse.
Your deadline is your own date. If your Chapter 13 is on file before it, the automatic stay generally stops the sale from going ahead. An earlier filing of yours can weaken that protection, so mention any past case.
We can file an emergency petition in a day or two (24 to 48 hours), or that same day when the sale is that close. We've filed on the day of a scheduled sale and stopped it.
Up to 10% every six months
Nassau County property taxes run high: the Census estimate for the median bill is top-coded at $10,000 or more a year. Fall behind, and the County Treasurer can sell a lien on your home at its annual tax lien sale.
The buyer's lien can carry interest and penalties of up to 10% of the purchase price for every six months, through the 24th month. You can redeem it until the Treasurer issues a tax deed or a foreclosure is started.
Ron uses three routes for property tax arrears:
The earlier a lien is dealt with, the less it has grown.

The foreclosure stays in Mineola

A Nassau County foreclosure is a state case in the Supreme Court in Mineola, separate from your bankruptcy in Central Islip. Filing Chapter 13 generally pauses it. The case is still there when the pause ends.
New York law (CPLR 3408) requires a settlement conference when a home loan is foreclosed on the house you live in, held within 60 days after proof of service is filed.
It exists to work through options such as a loan modification, a deed in lieu or a short sale. You can appear in person or through your lawyer.
Our foreclosure team defends the state case from the first response to an appeal, while the Chapter 13 runs in federal court.
Inside the bankruptcy, the court's Loss Mitigation Program (a supervised forum for working out a modification with your lender) runs only in some Central Islip judges' cases, so whether it is open to you is something we look into when we first meet.
The appeals record has a Nassau County result behind it. In FV-I, Inc. v Samuels (2025), a Nassau County homeowner's case, the Appellate Division, Second Department reversed a Nassau County Supreme Court order.
The court vacated the judgment of foreclosure and sale and dismissed the case as filed too late, under the statute of limitations and FAPA. We represented the homeowner.
Prior results do not guarantee a similar outcome.
A paused foreclosure is still a foreclosure, so we keep defending it.

Our experience, creativity and empathy allow us to legally represent you, effectively and affordably.
Book My Free ConsultationEvery cost in writing, first
Chapter 13 attorney fees are typically built into the court-approved repayment plan. In practice, the fee comes out of the same trustee payment that catches up the house.
Your consultation with Ron is free and stays free; it isn't credited against a fee later.
Every cost is disclosed in a written agreement before you sign anything. The filing fee is the court's own charge.
A county bar member who clerked for a bankruptcy judge

The firm belongs to the Nassau County Bar Association and the Suffolk County Bar Association, and to the National Association of Consumer Bankruptcy Attorneys and the American Bankruptcy Institute.

Ron was law clerk to Judge Prudence B. Abram of the U.S. Bankruptcy Court for the Southern District of New York. He held NYU Law's Galgay Fellowship in bankruptcy law, and his article on contempt power in bankruptcy court was published in 1989.

Your consultation is with Ron himself, by phone or in person. From then on you reach an attorney directly, never an intake desk, and the people who open your file stay with it.

Admitted to the Eastern District of New York's bar in 1992, four years into practice. Its Central Islip courthouse hears Nassau County cases.

Meet us in Mineola at 34 Willis Avenue, by appointment. Hablamos Español, and our team also speaks Hindi, Urdu and Russian.
Avvo 10.0 Superb · BBB A+ · Super Lawyers 2026 · Martindale-Hubbell Client Champion Platinum 2026
Every credential here is one you can look up.
What the house is worth, and what it owes
Tell us what the house is worth, what you owe on it and what the county says you owe in taxes. We'll show where that equity lands under Chapter 13, under Chapter 7, and if you modify the loan or fight the foreclosure instead.
Our legal consultations are free, but our advice may be invaluable.

Because the Central Islip courthouse is the federal bankruptcy court for both Nassau County and Suffolk County. What that means for travel:
Filed any time before the sale, a Chapter 13 generally stops it, though an earlier bankruptcy can limit that. Work with Nassau County's timing like this:
Up to $204,825 of it is shielded by the state's homestead exemption (as of April 1, 2024), if the house is your primary home. Above that, the house generally stays yours in Chapter 13; the extra equity instead raises the minimum your unsecured creditors must be paid through the plan, which can mean a bigger monthly payment.
Yes, it can. Chapter 13 can spread the tax arrears over as long as five years while any foreclosure or auction is stayed. Timing matters with a sold lien: it can only be redeemed until a tax deed issues or a foreclosure is started.
Usually, yes. Chapter 13 has no income limit of its own. It asks for regular income and debts within the federal limit: secured and unsecured debts combined below $2.75 million (the limit for cases filed after November 10, 2026). A higher income mostly changes the length: above the New York median for your household size, the plan generally runs five years, not three.
Generally, it goes on hold with the rest of the foreclosure. The automatic stay pauses the state case while your Chapter 13 is open. If the lender gets the stay lifted, or the bankruptcy ends, the foreclosure can pick up where it stopped.
Mineola. Our office at 34 Willis Avenue sees clients by appointment. Two other ways in:
One gets you current on the house; the other decides what everyone else is paid.
Chapter 7, Chapter 11 and the rest are laid out on our Nassau County bankruptcy services page.
Every bankruptcy option, county-wide.
When there's no house to protect.
When the business owes the debt.
How the chapter works, start to end.

Put a plan around your equity
Book online or call for a free consultation with Ron. If a Mineola auction is days away, say so first: when the date is that close, the petition can go in that same day.
Available 24/7.